Banks Probed on Bereavement and Power of Attorney Policies
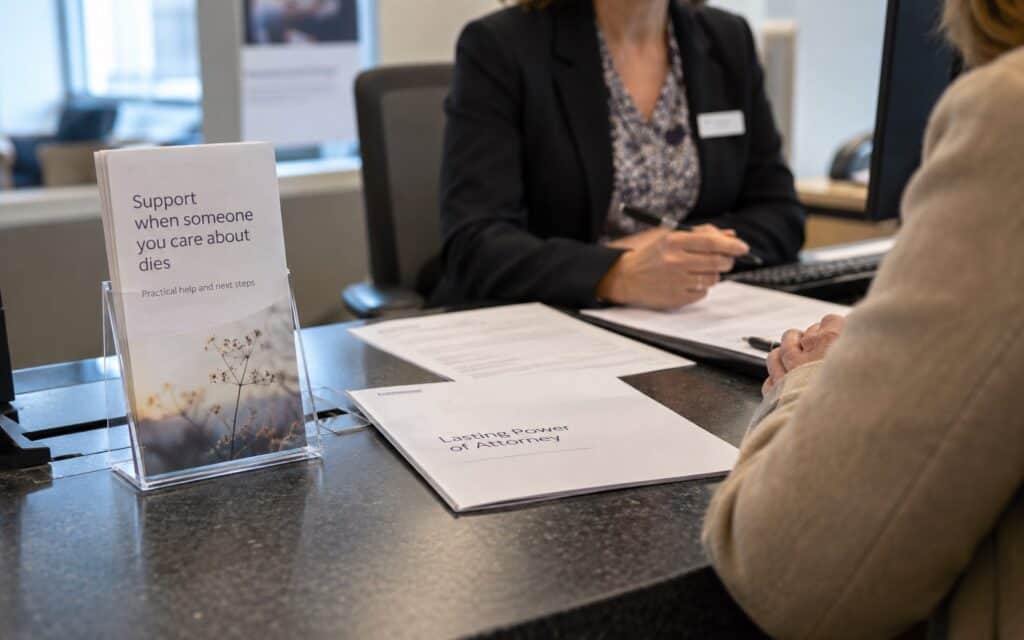
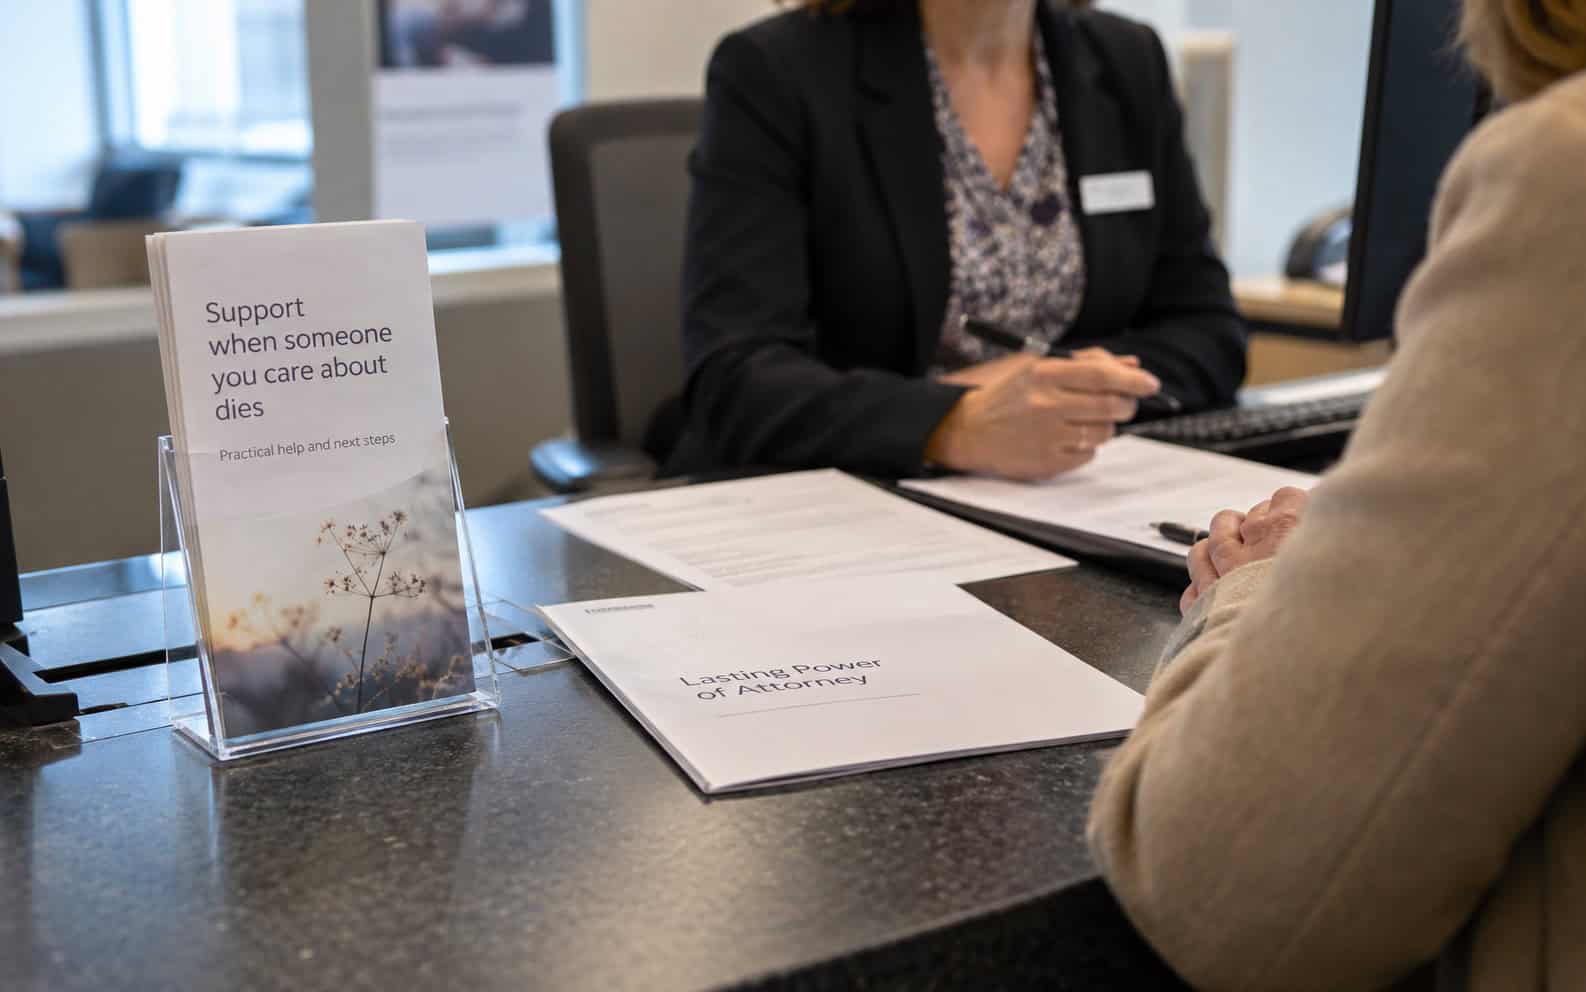
Banks and building societies have come under scrutiny over how they handle sensitive situations such as bereavement and powers of attorney. In April 2025, the Financial Conduct Authority (FCA) published the findings of a review of how retail banks and building societies treat customers in these vulnerable circumstances. It found that while some firms have improved under the Consumer Duty, others still fall short, causing delays and distress for customers and their representatives.
What the FCA found
The FCA reported that some firms are making a real difference, with clear policies and procedures and good use of data to identify customers’ needs and support them. Others were falling short. The review found that some staff were unclear about what action they needed to take and how quickly, and in some cases this meant people and their representatives could not access funds to pay essential bills. There were also examples of customers struggling to get support during an emergency, such as a mental health crisis.
The FCA highlighted areas for firms to focus on, including testing and monitoring customer outcomes, and joining up customer records across different parts of the business, so that bereaved customers and people acting under a power of attorney do not have to repeat information or have their cases lost between systems. It published examples of good and poor practice to help firms improve.
The Consumer Duty
The FCA’s Consumer Duty, which came into force in 2023, requires financial firms to deliver good outcomes for customers. It is particularly relevant when customers are in vulnerable circumstances, such as after a bereavement or when someone is managing another person’s money under a power of attorney.
Meeting those expectations means training staff to handle these situations consistently and with care, and making processes simple for people who are already under strain. As more people use digital tools to manage legal arrangements, services offering a power of attorney online, such as https://powerofattorneyonline.co.uk/, reflect the need for financial providers to integrate legal and financial processes smoothly.
Resources from organisations like Age UK reinforce the importance of accessible support and legal clarity, especially when someone is taking on decision-making responsibilities on behalf of another.
What this means for customers
| Situation | Practical tip |
|---|---|
| Registering a power of attorney with a bank | Ask what documents are needed and how long it will take; keep copies and a record of who you spoke to |
| Notifying a bank of a death | Ask whether it has a bereavement team and whether funds can be released for funeral costs |
| Dealing with several banks | Check whether a free notification service is available to tell several organisations at once |
| Poor service or delays | Complain to the firm first; if unresolved, you can go to the Financial Ombudsman Service |
An opportunity for banks
The review gives banks a clear opportunity to improve. Better training, clearer policies and more consistent service can make a real difference to customers at some of life’s hardest moments. Supporting people well through bereavement and legal changes is not just a regulatory requirement. It is a chance to show empathy, professionalism and care when it matters most.
Frequently asked questions
Do I need a registered power of attorney before a bank will deal with me?
For a lasting power of attorney in England and Wales, yes. It must be registered with the Office of the Public Guardian before it can be used. Banks will usually want to see the registered document or an approved copy before letting an attorney act on the account.
What can I do if a bank handles a bereavement badly?
Raise a complaint with the bank, explaining what went wrong and what you would like it to do. If you are not happy with the response, or it takes too long, you can usually refer the complaint to the Financial Ombudsman Service free of charge.
Where to go next
For why it pays to act early, read our article on why you shouldn’t delay registering a power of attorney.
